


Save 30% by using your HSA or FSA card
Build your home gym on pre-tax dollars
Illustrative, not a discount. Savings depend on tax rate and plan.
How does paying with HSA or FSA save me 30%?
These accounts exist for one thing: paying with pre-tax money for what treats, eases or prevents a condition a provider has diagnosed.
Try your own numbers
Federal, state and payroll tax combined. Most people land between 20% and 35%.
Tax you never pay
$779.70
on the Assisted Chin-Up / Dip at $2,599.00, paid with pre-tax dollars at 30%
Illustrative only, not tax advice. Your own rates and your plan decide what you save. Yearly limits are in IRS Publication 969.
What happens at checkout
Three steps, all of them inside the checkout you already use.
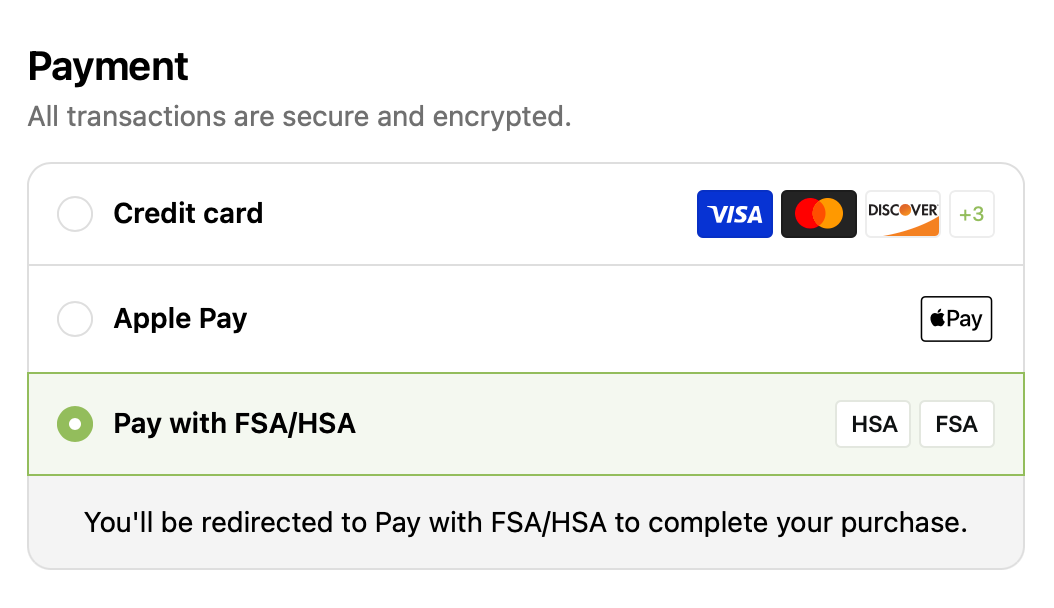
Pick HSA/FSA in the payment list
It sits with credit card and the wallets, not off in a separate flow.
Answer a few health questions
A licensed provider reviews your answers, not our products.

Pay, and your letter arrives by email
Use your HSA or FSA card, or split the order across two cards. Your letter of medical necessity arrives by email after you check out.

Shop HSA eligible items
 HSA eligibleC20$6,499Shop
 HSA eligibleAirBike Belt Drive$999Shop
 HSA eligibleAssisted Chin-Up / Dip$2,599Shop
 HSA eligibleUltimate 45 Degree Leg Press Hack Squat Combo$1,899Shop
 HSA eligibleMyRack Modular Power Rack$299Shop
 HSA eligibleBase Bench$499Shop
 HSA eligibleG20$5,999Shop
 HSA eligibleAirBike$699Shop
 HSA eligibleLeg Press / Calf Raise$2,599Shop
 HSA eligibleCompact Leg Press & Hack Squat$999Shop
 HSA eligiblePeak Flat Bench$299Shop
 HSA eligibleC10$4,699Shop
 HSA eligibleAir Rower$699Shop
 HSA eligibleChest / Shoulder Press$2,399Shop
 HSA eligibleM20From $3,999Shop
 HSA eligibleRear Deltoid / Pec Fly$2,399Shop
 HSA eligibleFunctional Trainer Rack (FTR)$3,399Shop
 HSA eligibleAbductor / Adductor$2,299Shop
 HSA eligibleM10From $2,999Shop
 HSA eligibleBicep / Tricep Machine$2,299Shop
 HSA eligibleTandem Tower (TT)$2,499Shop
 HSA eligibleLeg Extension / Leg Curl$2,299Shop
 HSA eligibleG3$1,999Shop
 HSA eligibleAbdominal / Back Extension$2,199Shop
 HSA eligibleX5(G1)$1,299Shop
 HSA eligibleLat Pulldown / Seated Row$2,199Shop
Before you worry about it
No new account
No new account to open and no balance to top up. Bring the card your employer gave you.
Your order is not held up
The questions do not hold up your order, so you pay and check out as normal.
A provider reviews you, not us
A licensed provider reviews your answers, not our products.
Normal cards still work
Yes. Credit card is still a payment option at checkout, alongside the wallets, and nothing about this page changes that.
Common questions
What are FSA and HSA accounts?
Both let you set aside money from your paycheck before taxes for eligible health expenses. An HSA is a health savings account and generally stays with you year after year. An FSA is a flexible spending account and usually has a yearly deadline. Not sure if you have one? Check with your employer or your benefits provider.
Can I use my HSA/FSA at Force USA?
Yes, on eligible equipment. Pick HSA/FSA in the payment list at checkout, answer a few quick health questions, and pay with your HSA or FSA card the same way you would use any other card. Fitness equipment needs a letter of medical necessity, so the questions matter. Your letter comes to you by email after you check out.
Can I use my regular credit card instead?
Yes. Every regular payment option is still there. You can also split an order: put part of it on your HSA or FSA card and the rest on a regular credit or debit card.
What is a letter of medical necessity?
Under IRS rules, some things you buy count as a medical expense only when they treat a specific health condition, not when they are for general health. A letter of medical necessity is a licensed provider's written opinion that a product may treat a condition you have.
Here is how it works. You answer a few health questions at checkout. A licensed provider reviews your answers, not our products. The questions do not hold up your order, so you pay and check out as normal. Your letter arrives by email after you check out. Keep it, because your plan may ask to see it. Not everyone qualifies, and your plan makes the final decision on any claim.
Are there any fees?
You pay the price on the product page. There is no extra charge at checkout for paying with your HSA or FSA card.
When should I use my FSA/HSA dollars?
Any time of year. HSA money generally stays with you year after year. FSA money usually has a deadline, and many plans run use it or lose it at the end of the year, so check your plan's dates before December.
How long until I get my letter of medical necessity?
It arrives by email after you check out. If you do not see it, check your spam folder first, then reach out to us through our contact page and we will help.
I don't have an HSA/FSA. Can I still benefit?
You need one of those accounts to use pre-tax money. Many employers offer them during open enrollment, so it is worth asking. You can still check out normally with any card.
I don't live in the US. Can I still use this?
HSA and FSA are United States programs, so the pre-tax option only applies to US accounts. Everything on the site can still be bought the normal way.
Use the card you already have
Pick HSA or FSA at checkout. Nothing else about your order changes.
See what is eligibleThe fine print
Some of what we sell may qualify as a medical expense under IRS rules. Eligible equipment needs a letter of medical necessity, which is a written opinion from a licensed provider that a product may treat a specific condition you have. That review is done by a licensed provider through an independent partner, not by Force USA. Not everyone qualifies. No product on this site has been reviewed or approved for you in advance.
A letter is not a guarantee that your plan will pay. Your plan administrator, the company that runs your HSA or FSA, makes that decision, and plans differ.
Force USA is not a tax advisor, a medical provider, or a benefits administrator, and nothing on this page is tax, legal, or medical advice. For questions about your account or a claim, contact your plan administrator. For tax questions, talk to a tax professional.
There is a yearly cap on how much you can put into one of these accounts. The IRS publishes the current numbers in Publication 969.